Last reviewed October 2026
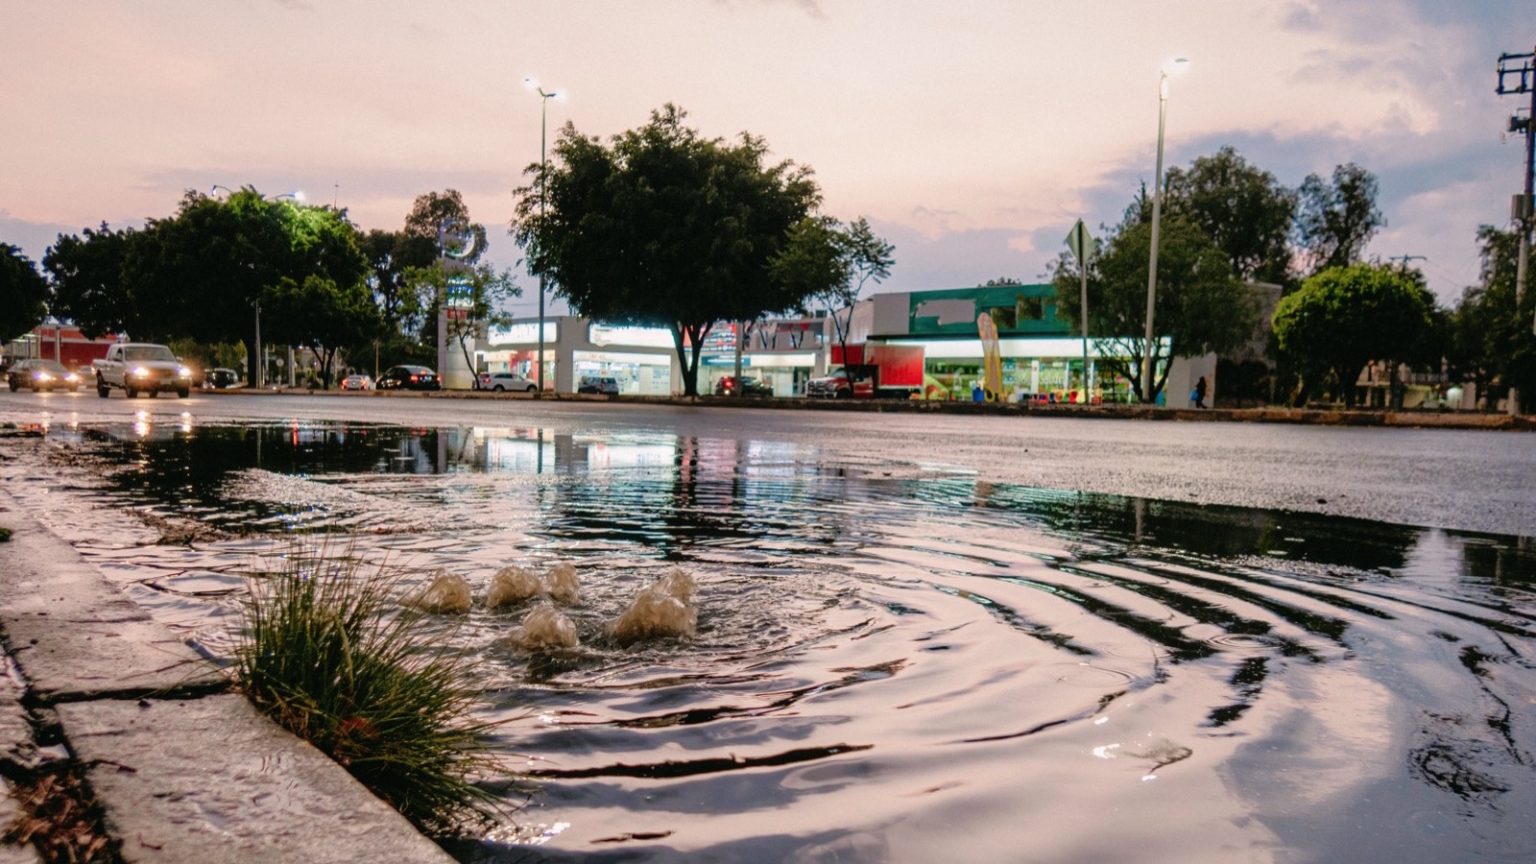
Flooding can happen in North Texas even far from a river. Before you buy or rent, it’s worth spending a few minutes checking a home’s flood risk. Here’s how to do it and what Texas law requires sellers and landlords to tell you.
Step 1: Look up the address on FEMA’s flood map
The Federal Emergency Management Agency maintains the Flood Map Service Center, which you can search by address at no cost. Look for whether the home is in a Special Flood Hazard Area, often called the “100-year floodplain.” Texas law defines that as an area FEMA designates as having a 1% or greater chance of flooding each year.
A map is a starting point, not a guarantee. Homes outside mapped flood zones can still flood from heavy rain or drainage problems. Ask about history, look at the lot’s grading, and talk with neighbors.
Step 2: Read the seller’s disclosure (buyers)
For most resale homes, Texas sellers must give buyers a Seller’s Disclosure Notice before the buyer is bound by the contract (Texas Property Code §5.008). The notice asks about flood-related items, including:
- Present flood insurance coverage
- Whether the property is wholly or partly in a 100-year floodplain
- Previous flooding, including flooding due to a reservoir failure or breach
If you receive the notice after signing the contract, the law lets you terminate for any reason within seven days. Read more in our post on the Texas Seller’s Disclosure Notice.
Step 3: Read the landlord’s flood notice (renters)
Texas landlords must give tenants a written notice, in a separate document at or before signing the lease, stating whether they know the dwelling is in a 100-year floodplain and whether it has flooded at least once in the last five years (Texas Property Code §92.0135). If neither box is checked, the law says to assume the dwelling is in a 100-year floodplain.
Step 4: Plan for flood insurance early
- Standard homeowners and renters policies typically don’t cover flood damage.
- National Flood Insurance Program policies typically have a 30-day waiting period before coverage begins, with some exceptions, such as when coverage is bought in connection with a mortgage, according to FloodSmart.
- If a lender requires flood insurance, get quotes before your option period ends so the cost is part of your decision.
Questions to ask
- Has the home ever flooded or had water enter the house?
- Has a flood insurance claim ever been filed?
- Where does water go during a heavy storm?
- Are there drainage easements or creeks nearby?
Comparing neighborhoods? Our community guides and house hunting guide can help. Or talk with a Clever Realtors agent.
Sources
- FEMA Flood Map Service Center
- FloodSmart: Flood Insurance 101
- Texas Property Code §5.008 (Seller’s Disclosure)
- Texas Property Code §92.0135 (Landlord flood disclosure)
This article is general information, not legal, tax, or financial advice. Rules and figures change, so confirm details with the official sources above or a qualified professional.
Share this article